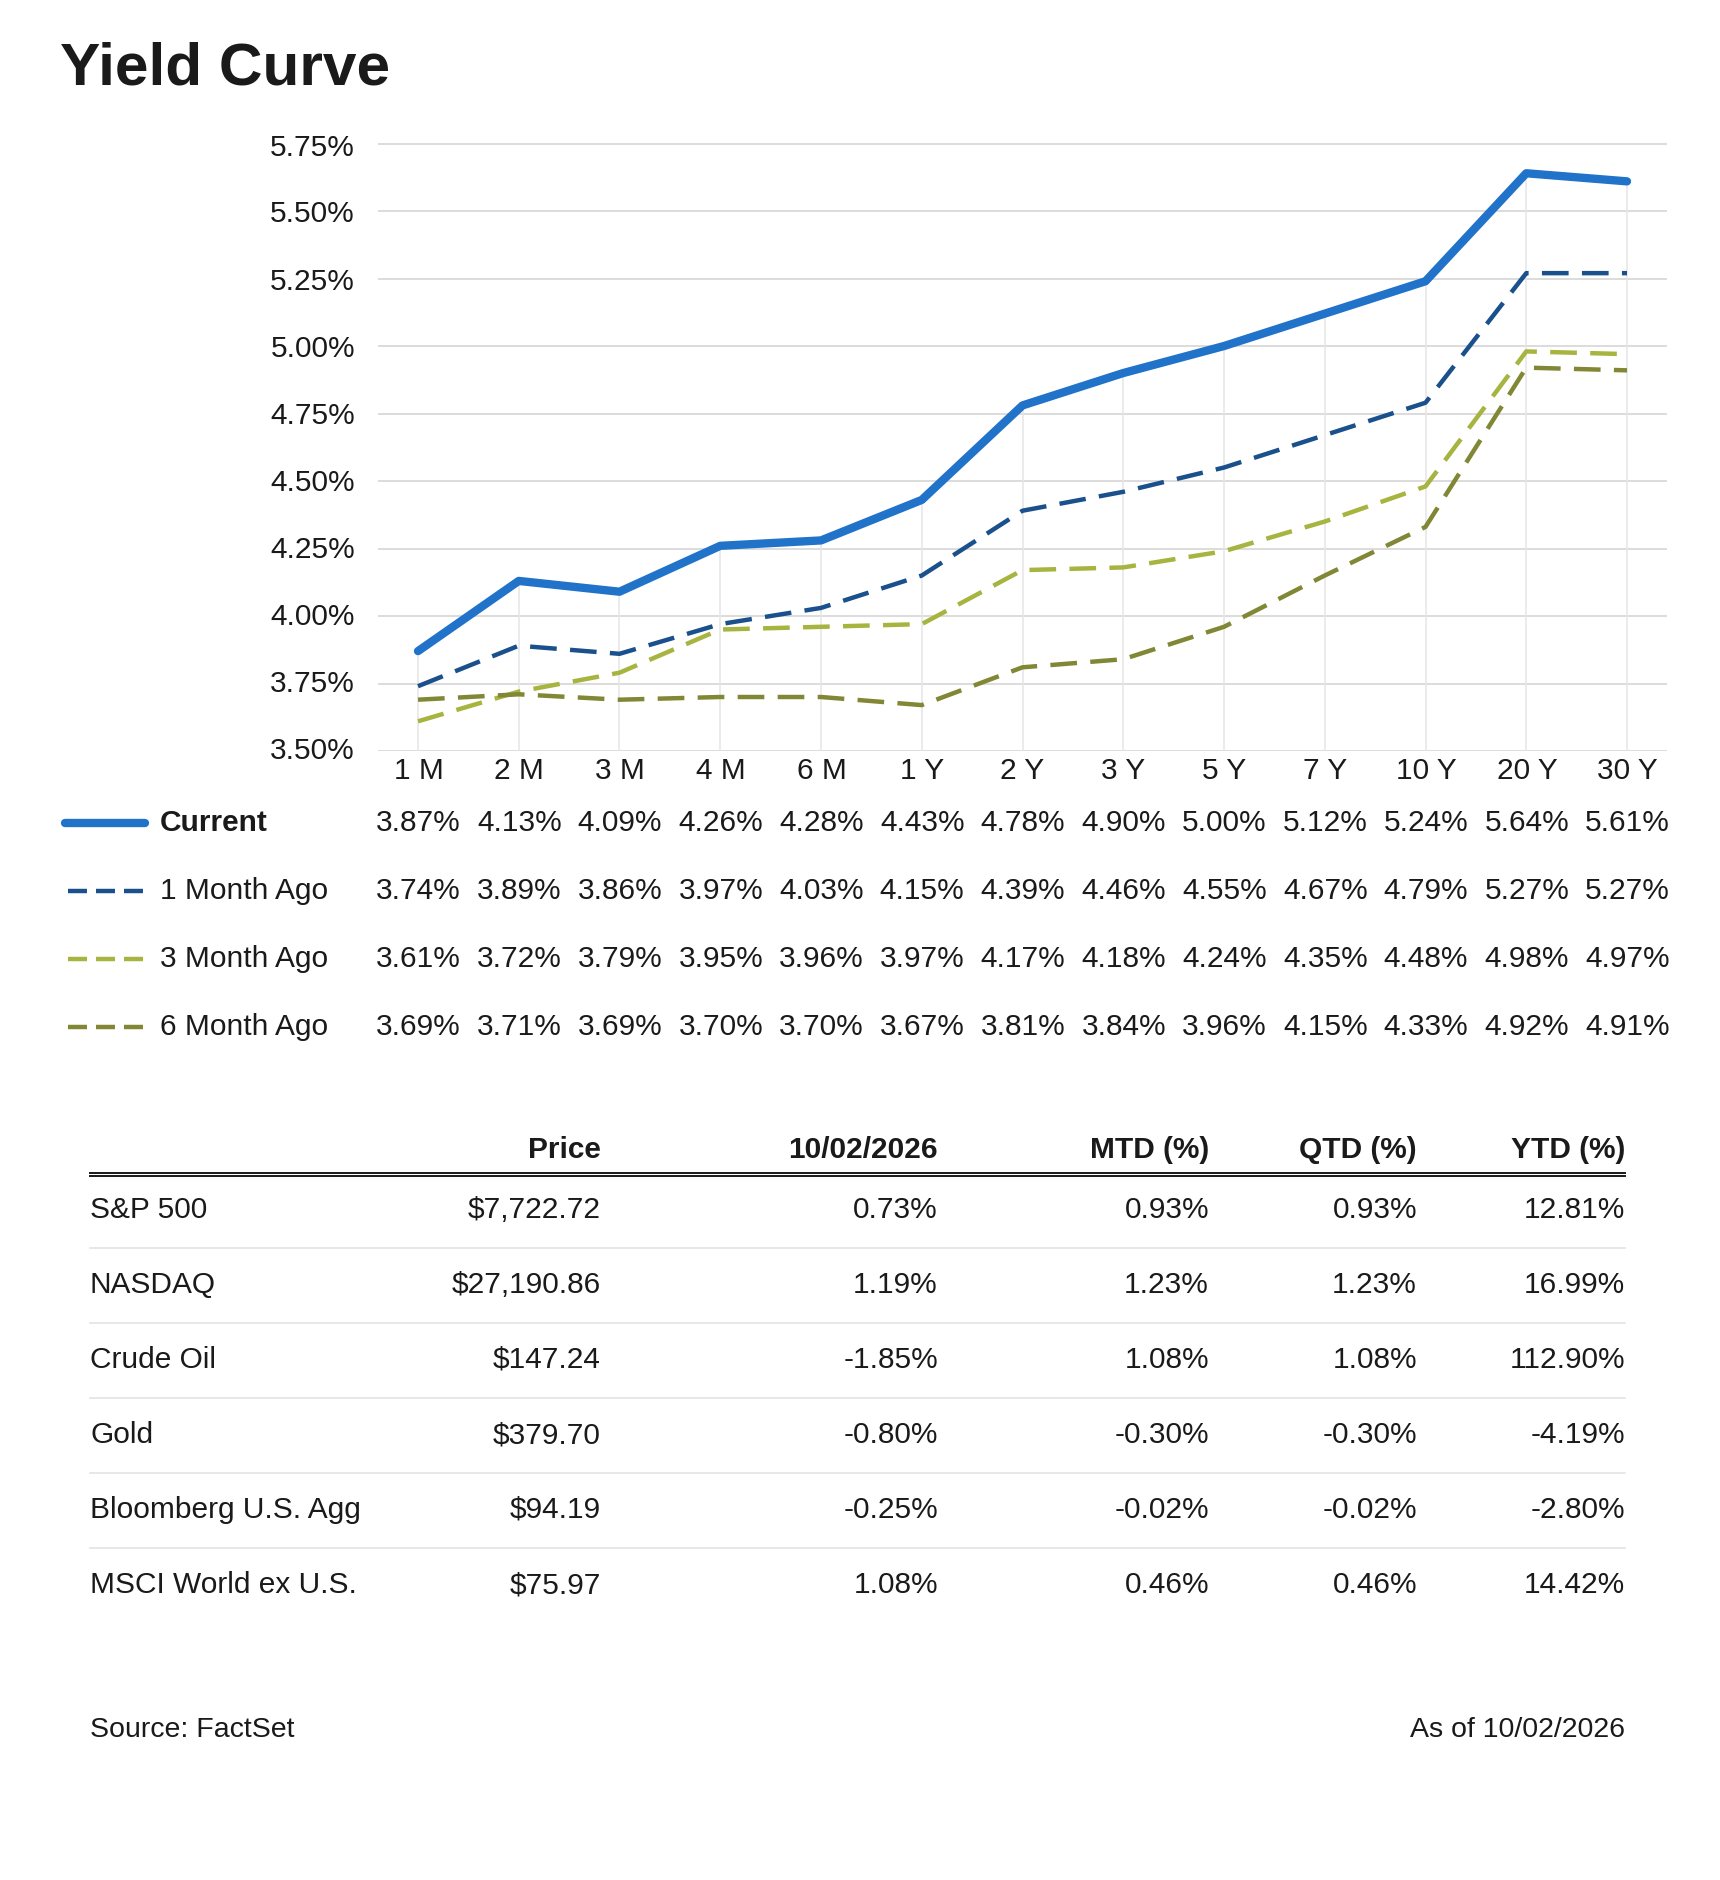
Major U.S. equities had a turbulent week last week – equities struggled in the beginning of the week due to another round of rising rates which later reversed in the latter half of the week as the market digested better inflation data and a weaker labor market report, adding support to the dovish narrative that the Fed could remain on hold in October. Early in the week, we saw treasury yields increase on the back of higher growth expectations, with the 10-year treasury yield at one point reaching 5.3% on Wednesday, the highest level since 2002. Midweek the PCE inflation numbers came in softer than expected, although part of the downside was driven by methodology changes to software, portfolio management fees, and legal services, which lowered the trend by roughly 36bps. Core PCE rose 0.25% for the month or 3% year-over-year, about 0.2% below what the Fed had anticipated. The labor market was weaker at the headline level, and unemployment moved up to 4.2%, but that was driven partially by new entrants as participation increased to 61.8%. As such, a softer inflation print and a weaker labor market lowered the probability of an October rate hike, causing equities to rally on Friday.
The market is not the economy, and the S&P 500 is not the average stock, and we are seeing this divergence. In the third quarter, the S&P 500 gained 2% while the S&P 500 Equal Weight fell 2%, as the largest companies continue to drive a larger share of index returns. As we enter the fourth quarter, it’s likely that we’ll see some short-term volatility in the markets as we approach the mid-term elections. However, we begin the fourth quarter from a better starting point, as higher rates have already compressed valuations, and we head into earnings season with consensus expecting 27% yoy EPS growth for Q3, bringing the earnings conversation back to the table.
September Jobs Report
The September jobs report came in weaker than expected, although the market digested the report positively as a weaker labor market adds support to the notion that the Fed doesn’t need to hike rates in October. Job gains for September were 29k, well below the 90k consensus expectations. Job gains were strongest in the healthcare (+17k), construction (+11k), and manufacturing industries (+9k) while job growth was weakest and negative in government (-17K), information (-10k), and professional and business services (-9k). The payrolls diffusion index declined by 8.6 to 49, its lowest reading since October 2025, which means that less than half of industries increased employment in September. Additionally, payroll numbers for July and August were both revised downward. The soft September headline number and the downward revisions brought the three-month payroll growth average down to 51k from 71k. The unemployment rate ticked up slightly to 4.2%, although half of the reason for the increase was due to an increase in the labor force participation rate. Average hourly earnings came in lower than expected, up just 0.1% for the month or 3% year-over-year. While not a strong report by any means, overall the labor market still doesn’t look too concerning. Put positively, the weak report suggests that the economy is not hot enough for the Fed to justify another hike in October, although there is the possibility that the October inflation report could come in strong and make the Fed’s decision very difficult.
August PCE
Inflation metrics in August came in slightly lighter than expected, but a deeper look at the report shows inflation remains persistent, and changes in methodology contributed to some of that cooling. Core PCE, the Fed’s preferred inflation gauge, rose 0.2% month over month (MoM) in August, versus expectations of 0.3%, and 3.0% year over year (YoY), versus expectations of 3.3%. The methodology changes affected three categories within core PCE: software and accessories, portfolio management fees, and legal services. Each category had reworks that either smoothed the data received or used a more direct price measure, yet they also helped the core reading appear lower than it otherwise would have. Still, the PCE trend remains stubborn, with August marking the 7th month that figures have stayed around 3.0%, a full percentage point above the Fed’s stated target. Meanwhile, real consumer spending remains resilient, with the MoM figure coming in at 0.6%, the highest MoM increase since March of 2025, though the strength was likely influenced by the timing of Amazon’s Prime Day sales. Still, the nominal figures in consumption were led by spending in nondurable goods, energy, and food services and accommodations. Markets initially reacted by dropping yields, but shortly after they quickly reversed and raised yields above pre-report levels, especially on the long end, showing that inflation concerns remain top of mind. On the short end, yields remained slightly below pre-report levels, and a shift in Fed futures shows a change in attitudes about how hawkish the Fed will be, with markets now pricing in a hold rather than a hike at the October meeting.
Lido Advisors, LLC is an SEC-registered investment adviser. Please note that SEC registration does not denote any particular competence or ability and no inference to the contrary should be made. For complete information on the services we provide and our fees, please review our Form ADV at adviserinfo.sec.gov, call 800-301-LIDO, or mail us at 1875 Century Park East Suite 950, Los Angeles, CA 90067.
The information contained herein reflects Lido’s views as of the date of this newsletter. Such views are subject to change at any time without notice due to changes in market or economic conditions and may not necessarily come to pass. Lido has obtained the information provided herein from various third-party sources believed to be reliable but such information is not guaranteed. Any forward-looking statements or forecasts are based on assumptions and actual results are expected to vary from any such statements or forecasts. No reliance should be placed on any such statements or forecasts when making any investment decision. Lido is not responsible for the consequences of any decisions or actions taken as a result of information provided in this newsletter and does not warrant or guarantee the accuracy or completeness of this information.
Past performance is not indicative of future performance. The information in this report is for informational purposes only and should not be relied upon as the basis of an investment or liquidation decision. Nothing in this report shall be construed to be a solicitation to buy or offer to sell any security, product or service to any non-U.S. investor, nor shall any such security, product or service be solicited, offered or sold in any jurisdiction where such activity would be contrary to the securities laws or other local laws and regulations or would subject Lido to any registration requirement within such jurisdiction. All content herein has been obtained from sources deemed to be reliable, but is subject to unintentional errors, omissions and changes without notice, and is not warranted as to its accuracy or completeness. You should not rely on the information contained herein, and should rely solely on, and carefully read, the appropriate offering and related subscription materials relating to any specific investment product before making any investment decision.
Not all investments are suitable for all clients. It should not be assumed that any security listed or any recommendations made in the future will be profitable or without loss, including risk of loss of principal, or will equal any prior performance. All investments involve the risk of potential investment losses including the potential risk of loss of principal as well as the potential for investment gain. Further, the prior performance figures indicated herein represent portfolio performance for only a short time period and may not be indicative of the returns or volatility each portfolio will generate over a long time period. The performance of the portfolios should also be viewed in the context of the broad market and general economic conditions prevailing during the periods covered by the performance information. Any references to future returns/risk are not promises of the actual return the client portfolio may achieve. Before investing, investors should seek financial advice regarding the appropriateness of investing in any securities of investment strategies discussed. Not all investments are suitable for all investors.
The information herein is not legal, such as trust or estate planning, advice, or tax advice. Any such information is provided for illustrative purposes only and must not be relied upon without the benefit of the advice of your lawyer and/or tax professional. Lido specifically disclaims any liability from any reliance on such information. Lido is not a legal service provider or tax professional and does not offer legal or tax advice. Should you desire to obtain tax or legal services or advice, you must enter into your own, independent engagement agreement with a licensed attorney or tax professional.
Lido specifically disclaims any and all liability arising from the information or illustrations presented in these materials and is not responsible for the consequences of any decisions or actions taken as a result.