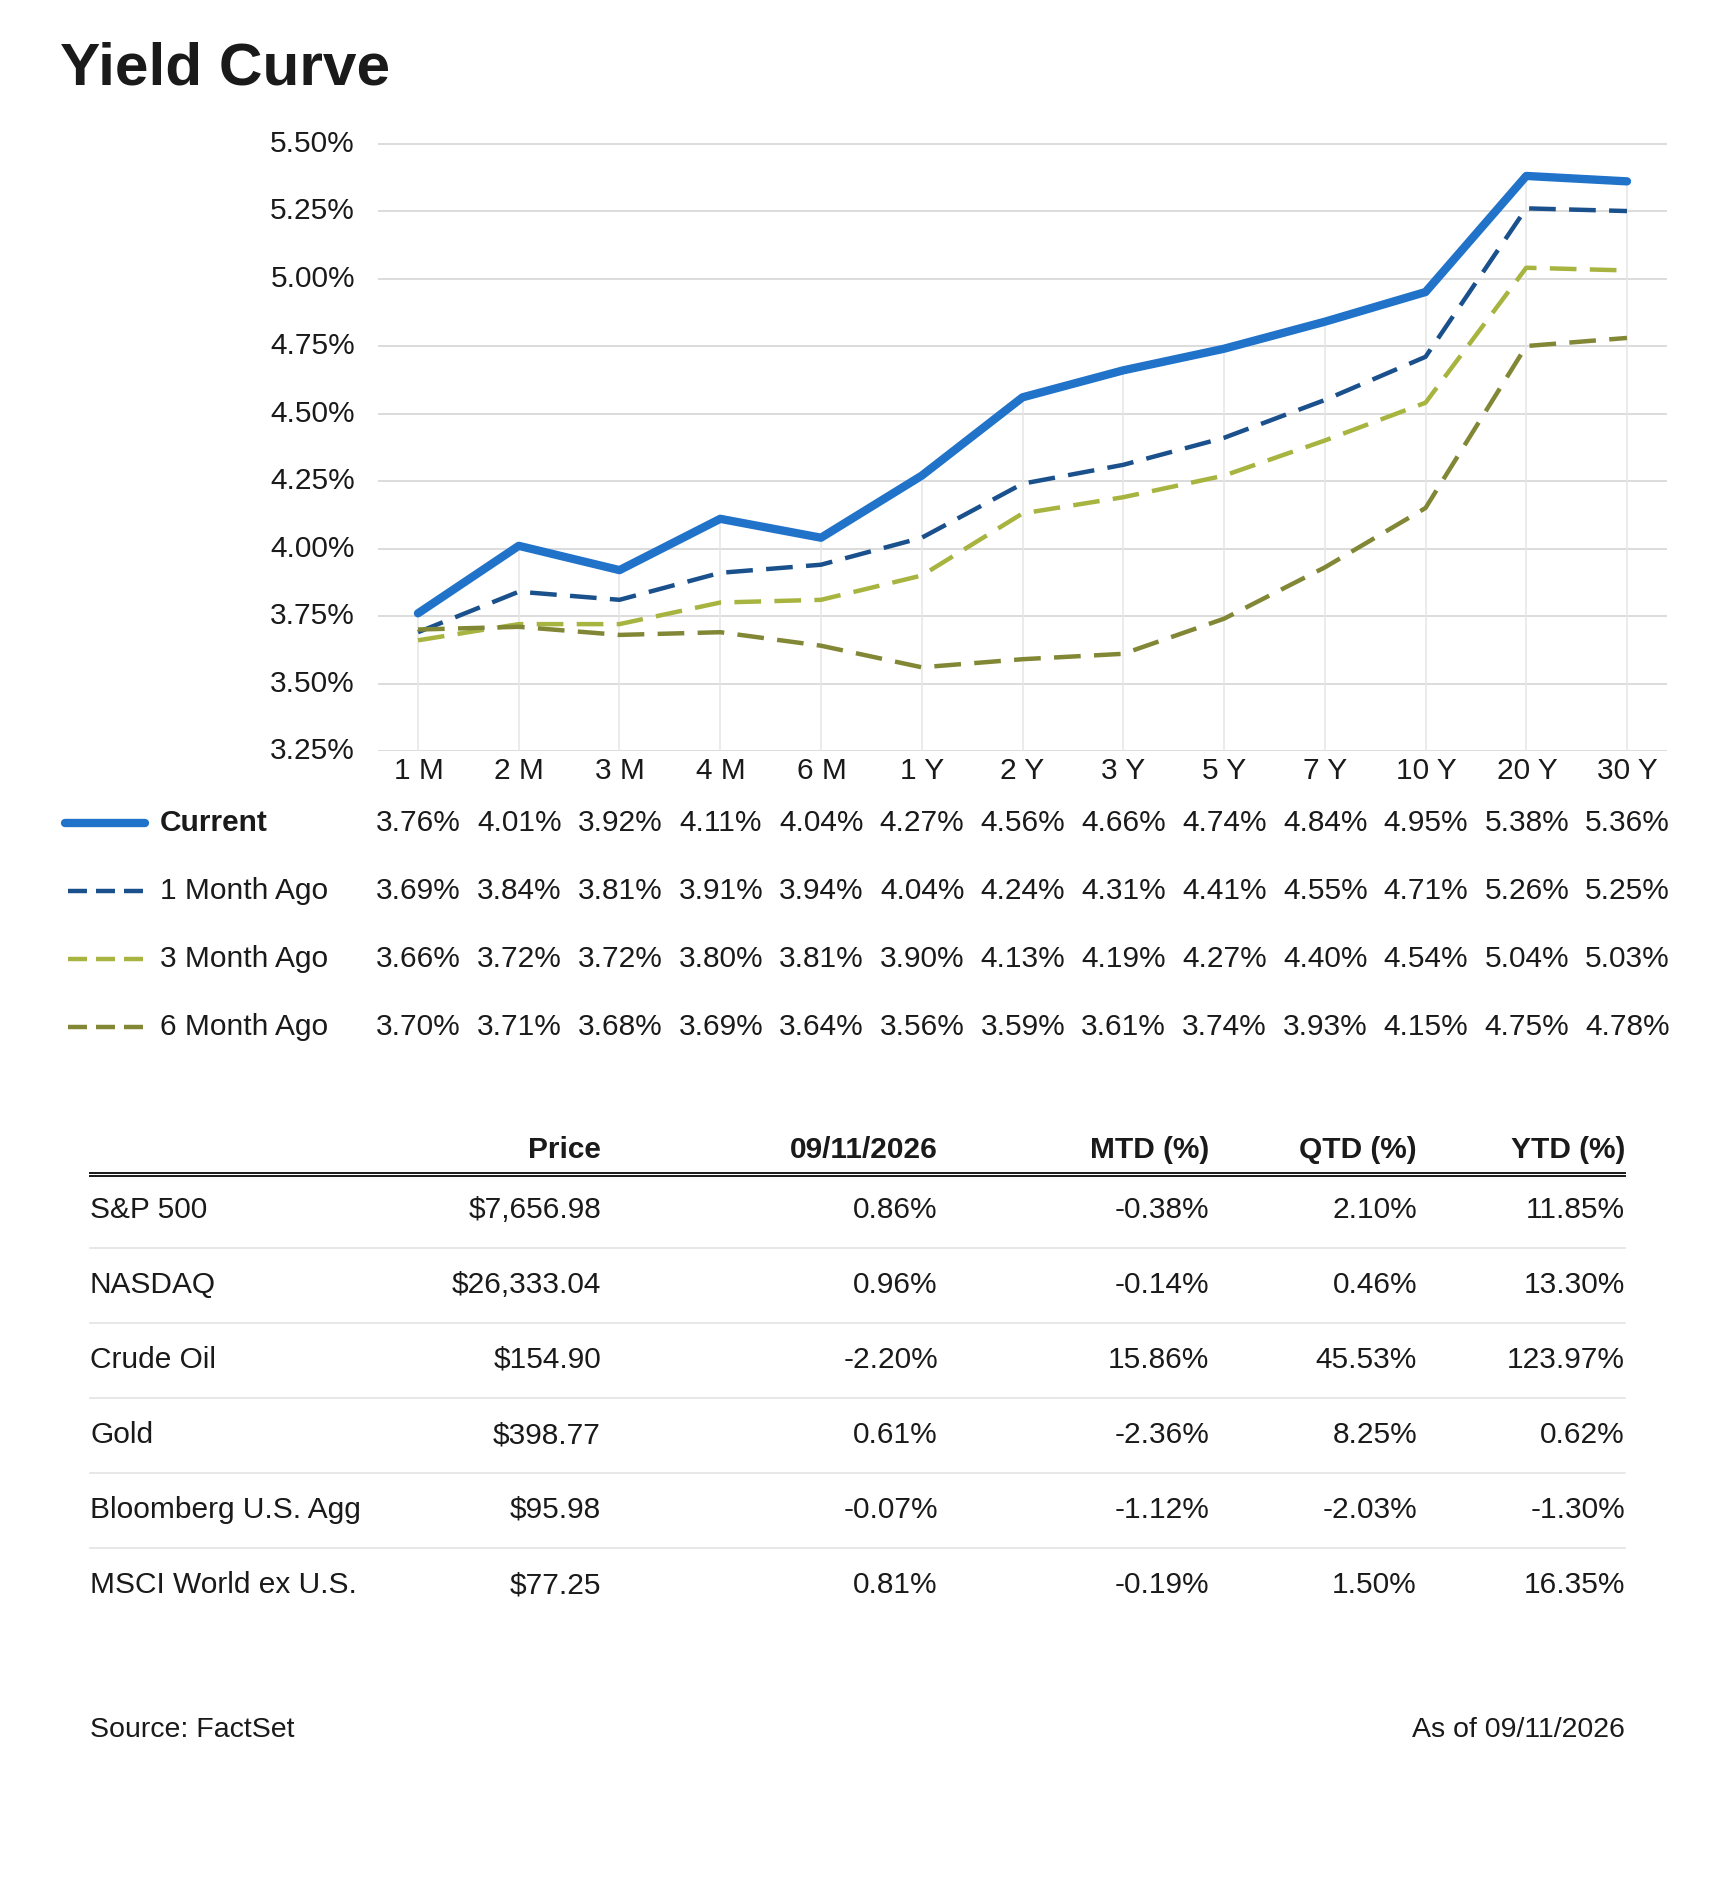
It’s all about rates. Higher inflation from the war in the Middle East, mounting fears around the US deficit, and the AI buildout competing for capital have all become the market’s main concerns. Debt held by the public is nearly 100% of GDP, and while the level itself isn’t the issue, the rising nominal interest expense and rates increasing closer to the US GDP growth rate are, we have been growing out of our debt, but that cushion is eroding and the AI buildout is only adding to the competition for capital thus pushing rates higher. As a result, the ten-year has increased to 4.97% on Friday, weighing on bond prices and equity valuations thus leaving the market lower for the week. Friday’s CPI print didn’t help, as Core CPI surprised to the upside (0.3% month-over-month, 2.4% year-over-year), shifting the market to price two hikes by year-end and two more next year. The Fed will likely hike 25bps this week, but the bigger question is the guidance, whether this is the start of another hiking cycle or just one and done.
August Consumer Price Index
Headline CPI came in line with expectations in August at 0.4% mom, holding the yoy at 3.4%. Core CPI surprised to the upside, rising 0.29% mom (2.4% yoy), but most of that surprise came from wireless phone service, which jumped 5.9% mom. However, this segment tends to reverse just as fast as it did after a similar spike in May. Stripping it out, core services ran a moderate 0.20%, with rent (0.17%) and OER (0.19%) both continuing to soften, medical services posting their weakest read in three years falling by 0.2%mom, and auto insurance still falling by 0.8%mom, thus keeping the disinflation trend in services stay intact. Core goods, on the other hand, rose 0.11% mom with the three-month pace climbing back to 0.9% from -0.7% in June. The increase in core good has been the result of higher computer hardware, which rose 3.8% after a 3.5% gain in July, and we are seeing higher prices in good as seen by Apple increase in prices, while the rise in memory costs we could see ongoing price increase in computer goods. Under the hood, the data continues to point to disinflation, particularly within core services, which carries significantly more weight in CPI. However, inflation remains above the Fed’s 2% target, while energy prices re-emerged as an upside risk following the Iran conflict, with oil now above $100/bbl. The risk has pushed the market toward pricing rate hikes in both September and December, compared with December previously.
A Peek into August Consumer Spending
Consumer spending remains the lifeline of the US economy, making up roughly 70% of GDP, so tracking its strength and resilience is highly important. Chase credit card data showed total US consumer spending grew 5.1% year-over-year in August, the third highest monthly reading this year, with discretionary spending equally robust at 5.4%, the second highest reading in 2026. On a two-year basis, which removes potential distortions, growth accelerated to 9.1% for total spending and 10.3% for discretionary. On the surface these numbers look healthy, but the growth is uneven depending on class. Upper income households drove much of the gain, with discretionary spending up 7.0% in August versus 5.2% for lower income households, a gap that continues to hold steady. Large retailers are already taking notice, such as Macy’s, who is being rewarded for “premiumizing” their stores with more high prices brands such as Coach and Ralph Lauren. This reliance on upper income spending highlights the fragility of both consumer discretionary sectors and a meaningful share of US GDP. The risk ahead is growing dependence on this cohort, as high energy prices and elevated rates weigh on lower end spending, and thereby leaves total spending more prone to equity market pullbacks, a risk upper income consumers are more directly tied to. A silver lining remains, however, as blue-collar wages have continued to outpace their white collars peers, which could result in a narrowing of the consumer gap. Yet, much of these wage gains remain tied to data center build out, which is also connected to the AI risk US equities are tied to.
Lido Advisors, LLC is an SEC-registered investment adviser. Please note that SEC registration does not denote any particular competence or ability and no inference to the contrary should be made. For complete information on the services we provide and our fees, please review our Form ADV at adviserinfo.sec.gov, call 800-301-LIDO, or mail us at 1875 Century Park East Suite 950, Los Angeles, CA 90067.
The information contained herein reflects Lido’s views as of the date of this newsletter. Such views are subject to change at any time without notice due to changes in market or economic conditions and may not necessarily come to pass. Lido has obtained the information provided herein from various third-party sources believed to be reliable but such information is not guaranteed. Any forward-looking statements or forecasts are based on assumptions and actual results are expected to vary from any such statements or forecasts. No reliance should be placed on any such statements or forecasts when making any investment decision. Lido is not responsible for the consequences of any decisions or actions taken as a result of information provided in this newsletter and does not warrant or guarantee the accuracy or completeness of this information.
Past performance is not indicative of future performance. The information in this report is for informational purposes only and should not be relied upon as the basis of an investment or liquidation decision. Nothing in this report shall be construed to be a solicitation to buy or offer to sell any security, product or service to any non-U.S. investor, nor shall any such security, product or service be solicited, offered or sold in any jurisdiction where such activity would be contrary to the securities laws or other local laws and regulations or would subject Lido to any registration requirement within such jurisdiction. All content herein has been obtained from sources deemed to be reliable, but is subject to unintentional errors, omissions and changes without notice, and is not warranted as to its accuracy or completeness. You should not rely on the information contained herein, and should rely solely on, and carefully read, the appropriate offering and related subscription materials relating to any specific investment product before making any investment decision.
Not all investments are suitable for all clients. It should not be assumed that any security listed or any recommendations made in the future will be profitable or without loss, including risk of loss of principal, or will equal any prior performance. All investments involve the risk of potential investment losses including the potential risk of loss of principal as well as the potential for investment gain. Further, the prior performance figures indicated herein represent portfolio performance for only a short time period and may not be indicative of the returns or volatility each portfolio will generate over a long time period. The performance of the portfolios should also be viewed in the context of the broad market and general economic conditions prevailing during the periods covered by the performance information. Any references to future returns/risk are not promises of the actual return the client portfolio may achieve. Before investing, investors should seek financial advice regarding the appropriateness of investing in any securities of investment strategies discussed. Not all investments are suitable for all investors.
The information herein is not legal, such as trust or estate planning, advice, or tax advice. Any such information is provided for illustrative purposes only and must not be relied upon without the benefit of the advice of your lawyer and/or tax professional. Lido specifically disclaims any liability from any reliance on such information. Lido is not a legal service provider or tax professional and does not offer legal or tax advice. Should you desire to obtain tax or legal services or advice, you must enter into your own, independent engagement agreement with a licensed attorney or tax professional.
Lido specifically disclaims any and all liability arising from the information or illustrations presented in these materials and is not responsible for the consequences of any decisions or actions taken as a result.
Lido Advisors, LLC is an SEC-registered investment adviser. Please note that SEC registration does not denote any particular competence or ability and no inference to the contrary should be made. For complete information on the services we provide and our fees, please review our Form ADV at adviserinfo.sec.gov, call 800-301-LIDO, or mail us at 1875 Century Park East Suite 950, Los Angeles, CA 90067.
The information contained herein reflects Lido’s views as of the date of this newsletter. Such views are subject to change at any time without notice due to changes in market or economic conditions and may not necessarily come to pass. Lido has obtained the information provided herein from various third-party sources believed to be reliable but such information is not guaranteed. Any forward-looking statements or forecasts are based on assumptions and actual results are expected to vary from any such statements or forecasts. No reliance should be placed on any such statements or forecasts when making any investment decision. Lido is not responsible for the consequences of any decisions or actions taken as a result of information provided in this newsletter and does not warrant or guarantee the accuracy or completeness of this information.
Past performance is not indicative of future performance. The information in this report is for informational purposes only and should not be relied upon as the basis of an investment or liquidation decision. Nothing in this report shall be construed to be a solicitation to buy or offer to sell any security, product or service to any non-U.S. investor, nor shall any such security, product or service be solicited, offered or sold in any jurisdiction where such activity would be contrary to the securities laws or other local laws and regulations or would subject Lido to any registration requirement within such jurisdiction. All content herein has been obtained from sources deemed to be reliable, but is subject to unintentional errors, omissions and changes without notice, and is not warranted as to its accuracy or completeness. You should not rely on the information contained herein, and should rely solely on, and carefully read, the appropriate offering and related subscription materials relating to any specific investment product before making any investment decision.
Not all investments are suitable for all clients. It should not be assumed that any security listed or any recommendations made in the future will be profitable or without loss, including risk of loss of principal, or will equal any prior performance. All investments involve the risk of potential investment losses including the potential risk of loss of principal as well as the potential for investment gain. Further, the prior performance figures indicated herein represent portfolio performance for only a short time period and may not be indicative of the returns or volatility each portfolio will generate over a long time period. The performance of the portfolios should also be viewed in the context of the broad market and general economic conditions prevailing during the periods covered by the performance information. Any references to future returns/risk are not promises of the actual return the client portfolio may achieve. Before investing, investors should seek financial advice regarding the appropriateness of investing in any securities of investment strategies discussed. Not all investments are suitable for all investors.
The information herein is not legal, such as trust or estate planning, advice, or tax advice. Any such information is provided for illustrative purposes only and must not be relied upon without the benefit of the advice of your lawyer and/or tax professional. Lido specifically disclaims any liability from any reliance on such information. Lido is not a legal service provider or tax professional and does not offer legal or tax advice. Should you desire to obtain tax or legal services or advice, you must enter into your own, independent engagement agreement with a licensed attorney or tax professional.
Lido specifically disclaims any and all liability arising from the information or illustrations presented in these materials and is not responsible for the consequences of any decisions or actions taken as a result.