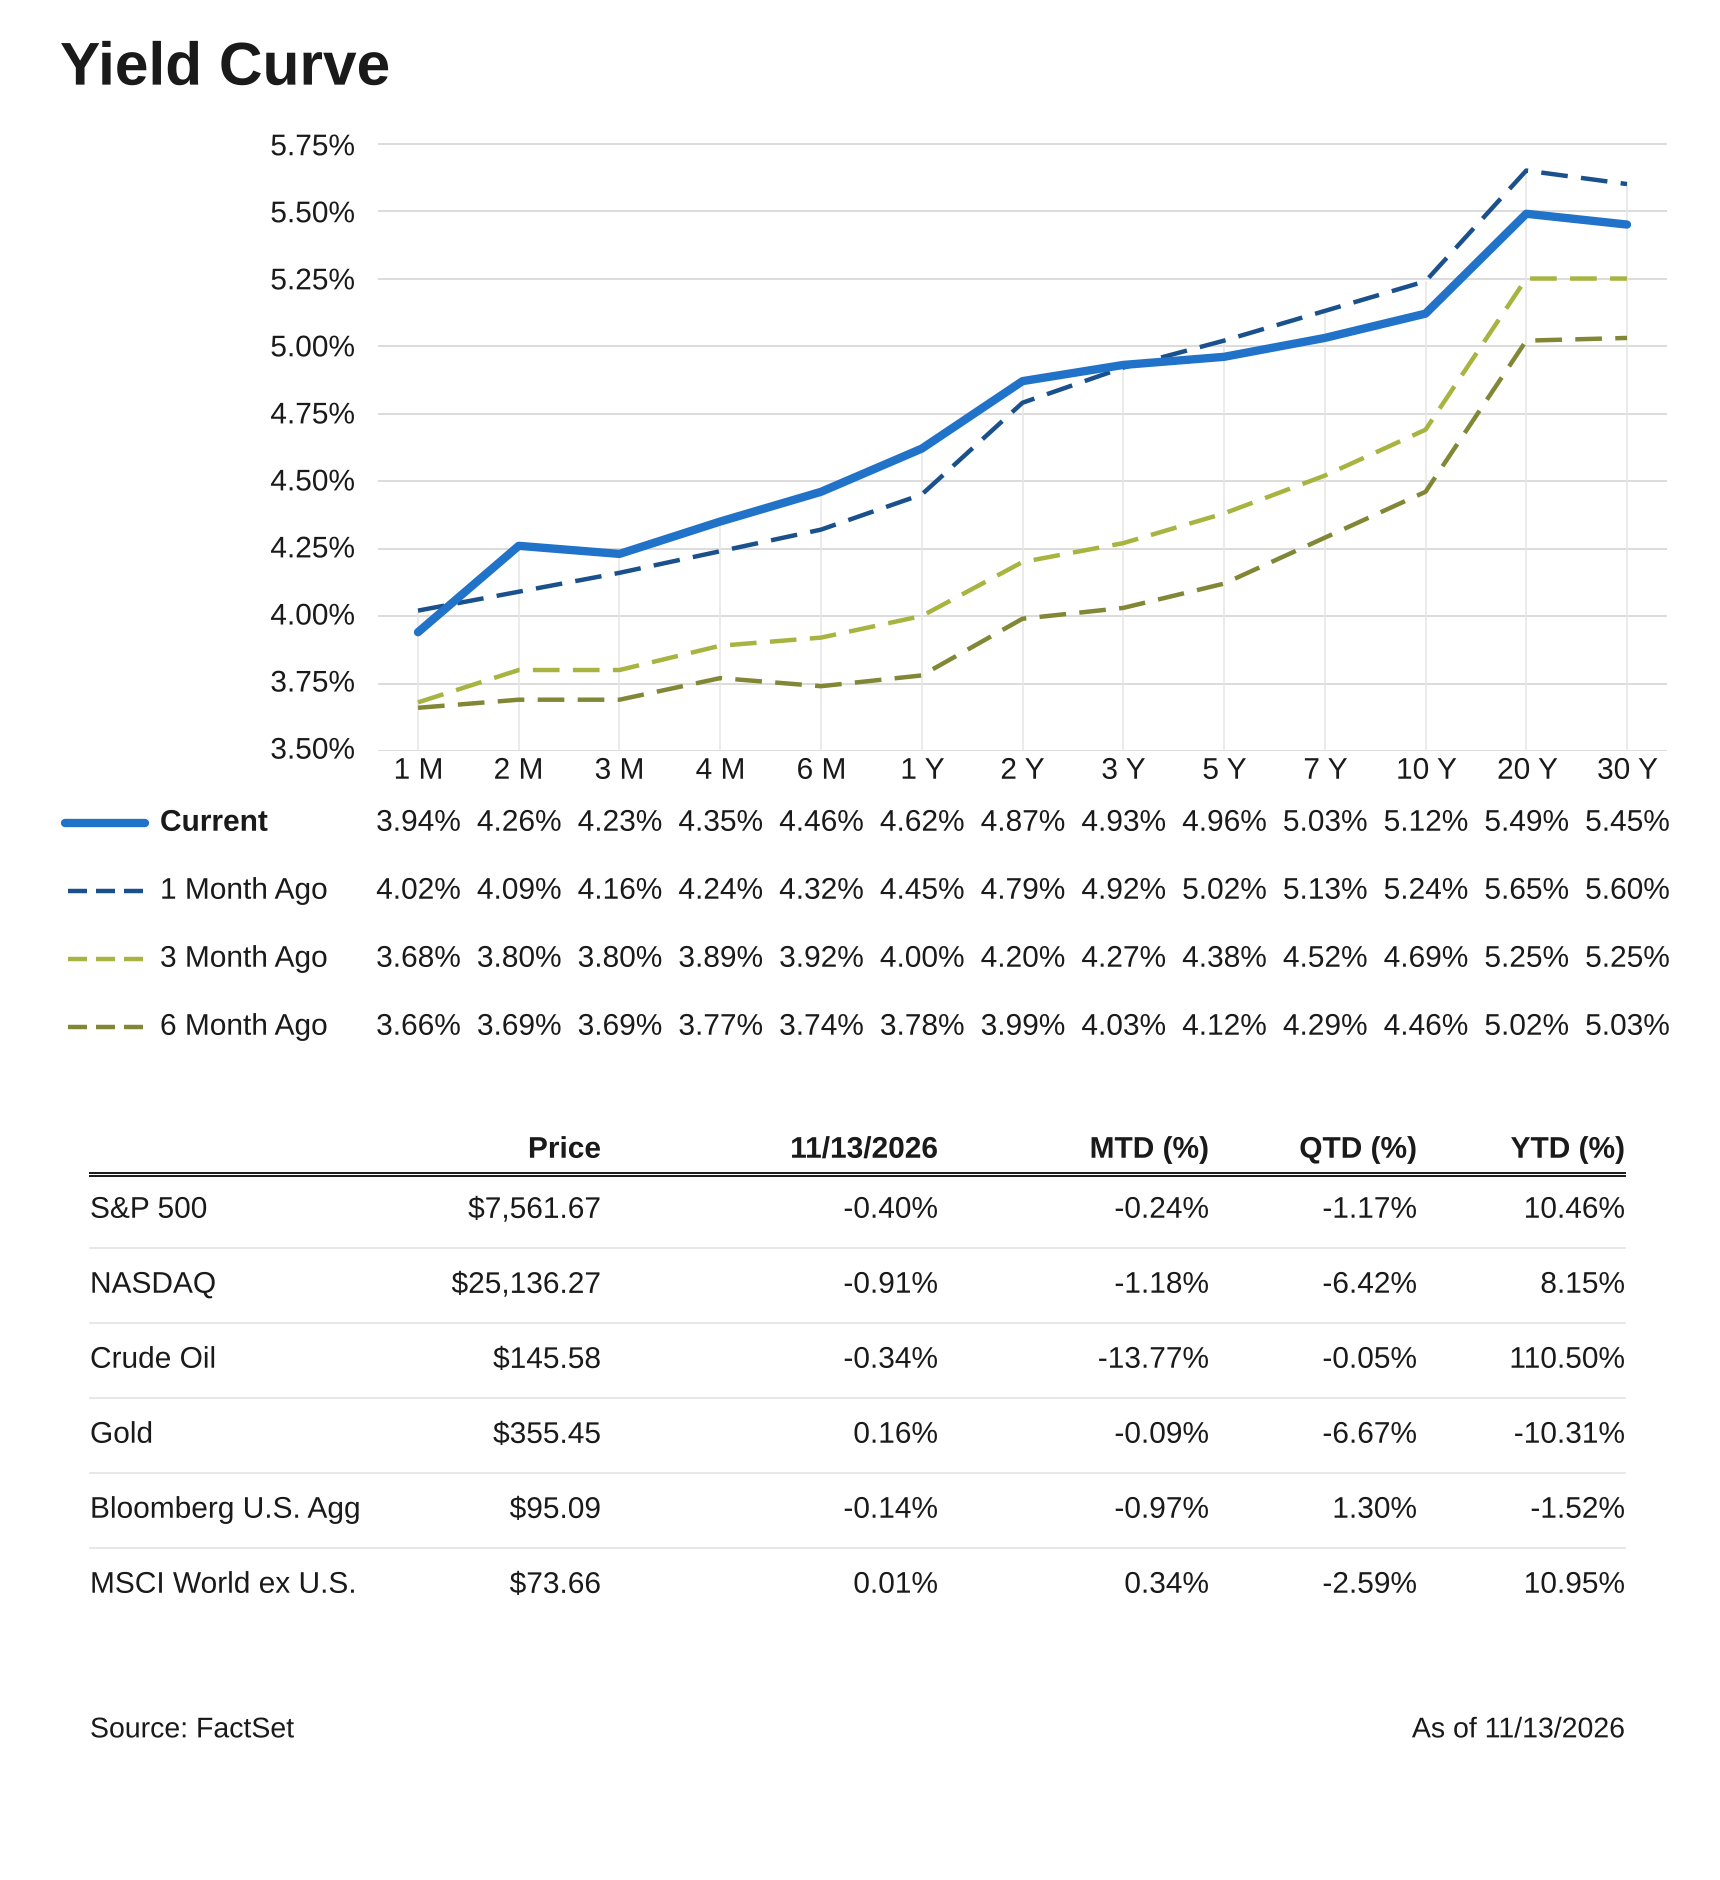
Markets had a lot to absorb last week and still came out ahead. October’s CPI ran hotter than expected, and the increases showed up across most categories. That breadth is the signal Fed Chair Warsh watches closely, and it pushed 2- and 10-year Treasury yields up about 30 basis points. Normally that would weigh on stocks, but the S&P 500 gained roughly 2.5% and the Nasdaq 3.6%. Much of the explanation is positioning: the prior week’s sell-off, the worst since April 2025, had left investors light on risk, especially in tech, and lower oil prices early in the week gave them a reason to buy back in.
That same reading of the data explains the muted response to Governor Waller’s call for a possible 50 basis point hike. With a December move already priced in, his comments changed the timing more than the destination. A larger hike now would largely pull forward one the market already expects early next year.
Within AI, the story was rotation and not a retreat. Nvidia fell nearly 13% after Huang’s troubles, but the money stayed in the sector. It moved toward other chipmakers like AMD and Broadcom on expectations that they will gain market share, lifting the broader semiconductor group 7%.
The bigger question the market is now grappling with is what drives returns from here. Earnings growth remains healthy but is slowing, from more than 30% this year to an expected 11% next year. With inflation sticky and the Fed still tightening, there is little room for valuations to expand. That leaves earnings to do the heavy lifting as the main driver of returns next year.
This week, NVDA reports earnings on Tuesday, with investors focused on any update on leadership following Jensen Huang’s resignation. Anthropic is expected to price its IPO on Wednesday and begin trading Thursday at a valuation of up to $1.4 trillion.
Inflation – CPI
October’s CPI suggests inflation is broadening beyond oil and the conflict with Iran, which we think makes a December hike more likely. Core came in above expectations, led by services. Services ex-housing rose 0.40%, driven by recreation services (0.9%), where nearly every category moved higher, from streaming subscriptions to shopping club memberships, along with car insurance (0.7%) and medical services (0.3%). Core goods rose a modest 0.16%, but only because used-car prices fell 1.2%. Excluding vehicles, goods rose 0.45%, the second-largest gain since COVID. Household furnishings (0.7%) turned higher after falling since February, as the relief from the end of IEEPA tariffs fades and higher shipping costs add pressure, while medical goods and tech products also rose. Given the breadth of the report, it becomes harder for the Fed to look past inflation. With November CPI due one day after the December meeting, this was the last reading the Fed sees before it decides. As a result, 2- to 5-year yields led the move higher, and markets now price three to four hikes through 2027, up from two to three. However, we see reasons some of this pressure may fade. Oil has fallen sharply on hopes for a diplomatic resolution, which should ease energy and transportation costs feeding into goods. More importantly, wages are not driving the increase: the labor market remains balanced, and wage growth has slowed to 3.09%, below headline inflation. That makes a sustained wage-price cycle less likely.
Anthropic Looks to Make History with Its IPO
After Nvidia’s scandal last week, markets are quickly shifting their attention to the Anthropic IPO (ticker: ANT) next week, which is looking to make history by raising $90.4 billion, the largest IPO ever, and to serve as a gauge for the strength of the AI trade. Appetite for ANT appears to remain high. The IPO is more than six times oversubscribed, with about 20% of its shares reportedly aimed at retail investors, and the company is targeting a fully diluted valuation of $1.4 trillion. ANT’s arrival matters because, until now, investors could buy only the picks and shovels of the AI trade or AI-adjacent companies with other business segments, but ANT is the first pure-play frontier LLM company to go public, giving a clear signal on how enterprise adoption of AI is unfolding. Another crucial new catalyst that ANT brings to the market is around its spending plans, as right now ANT has a total spending commitment of $901 billion, and it will have to carefully balance the line between spending more compute to make sure it’s able to continue remaining at the frontier and making sure the company has a roadmap to profitability for its shareholders. That’s exactly why revenue growth continues to remain at the forefront of investors’ minds. Its latest figures showed that annualized revenue run rate (ARR) grew from $65 billion in July of this year to $81 billion as of October 31, giving confidence that ANT can continue to outgrow its high infrastructure bill, which is expected to be as high as $71 billion by September 30 of next year. If markets have concerns about growth, or any piece of the AI narrative breaks down, valuation will reflect that. As of now, ANT is planned to debut at a 17x ARR valuation multiple, serving as a useful snapshot for investors to compare if growth assumptions change and setting the landscape as a benchmark for future AI companies to IPO, particularly its main rival, OpenAI. The key dates to watch now are Nov. 18 and 19: the former is the pricing date for ANT shares, and the latter is the first trading day, crucial for gauging whether conviction in the AI trade remains firm or has softened.
Lido Advisors, LLC is an SEC-registered investment adviser. Please note that SEC registration does not denote any particular competence or ability and no inference to the contrary should be made. For complete information on the services we provide and our fees, please review our Form ADV at adviserinfo.sec.gov, call 800-301-LIDO, or mail us at 1875 Century Park East Suite 950, Los Angeles, CA 90067.
The information contained herein reflects Lido’s views as of the date of this newsletter. Such views are subject to change at any time without notice due to changes in market or economic conditions and may not necessarily come to pass. Lido has obtained the information provided herein from various third-party sources believed to be reliable but such information is not guaranteed. Any forward-looking statements or forecasts are based on assumptions and actual results are expected to vary from any such statements or forecasts. No reliance should be placed on any such statements or forecasts when making any investment decision. Lido is not responsible for the consequences of any decisions or actions taken as a result of information provided in this newsletter and does not warrant or guarantee the accuracy or completeness of this information.
Past performance is not indicative of future performance. The information in this report is for informational purposes only and should not be relied upon as the basis of an investment or liquidation decision. Nothing in this report shall be construed to be a solicitation to buy or offer to sell any security, product or service to any non-U.S. investor, nor shall any such security, product or service be solicited, offered or sold in any jurisdiction where such activity would be contrary to the securities laws or other local laws and regulations or would subject Lido to any registration requirement within such jurisdiction. All content herein has been obtained from sources deemed to be reliable, but is subject to unintentional errors, omissions and changes without notice, and is not warranted as to its accuracy or completeness. You should not rely on the information contained herein, and should rely solely on, and carefully read, the appropriate offering and related subscription materials relating to any specific investment product before making any investment decision.
Not all investments are suitable for all clients. It should not be assumed that any security listed or any recommendations made in the future will be profitable or without loss, including risk of loss of principal, or will equal any prior performance. All investments involve the risk of potential investment losses including the potential risk of loss of principal as well as the potential for investment gain. Further, the prior performance figures indicated herein represent portfolio performance for only a short time period and may not be indicative of the returns or volatility each portfolio will generate over a long time period. The performance of the portfolios should also be viewed in the context of the broad market and general economic conditions prevailing during the periods covered by the performance information. Any references to future returns/risk are not promises of the actual return the client portfolio may achieve. Before investing, investors should seek financial advice regarding the appropriateness of investing in any securities of investment strategies discussed. Not all investments are suitable for all investors.
The information herein is not legal, such as trust or estate planning, advice, or tax advice. Any such information is provided for illustrative purposes only and must not be relied upon without the benefit of the advice of your lawyer and/or tax professional. Lido specifically disclaims any liability from any reliance on such information. Lido is not a legal service provider or tax professional and does not offer legal or tax advice. Should you desire to obtain tax or legal services or advice, you must enter into your own, independent engagement agreement with a licensed attorney or tax professional.
Lido specifically disclaims any and all liability arising from the information or illustrations presented in these materials and is not responsible for the consequences of any decisions or actions taken as a result.
Lido Advisors, LLC is an SEC-registered investment adviser. Please note that SEC registration does not denote any particular competence or ability and no inference to the contrary should be made. For complete information on the services we provide and our fees, please review our Form ADV at adviserinfo.sec.gov, call 800-301-LIDO, or mail us at 1875 Century Park East Suite 950, Los Angeles, CA 90067.
The information contained herein reflects Lido’s views as of the date of this newsletter. Such views are subject to change at any time without notice due to changes in market or economic conditions and may not necessarily come to pass. Lido has obtained the information provided herein from various third-party sources believed to be reliable but such information is not guaranteed. Any forward-looking statements or forecasts are based on assumptions and actual results are expected to vary from any such statements or forecasts. No reliance should be placed on any such statements or forecasts when making any investment decision. Lido is not responsible for the consequences of any decisions or actions taken as a result of information provided in this newsletter and does not warrant or guarantee the accuracy or completeness of this information.
Past performance is not indicative of future performance. The information in this report is for informational purposes only and should not be relied upon as the basis of an investment or liquidation decision. Nothing in this report shall be construed to be a solicitation to buy or offer to sell any security, product or service to any non-U.S. investor, nor shall any such security, product or service be solicited, offered or sold in any jurisdiction where such activity would be contrary to the securities laws or other local laws and regulations or would subject Lido to any registration requirement within such jurisdiction. All content herein has been obtained from sources deemed to be reliable, but is subject to unintentional errors, omissions and changes without notice, and is not warranted as to its accuracy or completeness. You should not rely on the information contained herein, and should rely solely on, and carefully read, the appropriate offering and related subscription materials relating to any specific investment product before making any investment decision.
Not all investments are suitable for all clients. It should not be assumed that any security listed or any recommendations made in the future will be profitable or without loss, including risk of loss of principal, or will equal any prior performance. All investments involve the risk of potential investment losses including the potential risk of loss of principal as well as the potential for investment gain. Further, the prior performance figures indicated herein represent portfolio performance for only a short time period and may not be indicative of the returns or volatility each portfolio will generate over a long time period. The performance of the portfolios should also be viewed in the context of the broad market and general economic conditions prevailing during the periods covered by the performance information. Any references to future returns/risk are not promises of the actual return the client portfolio may achieve. Before investing, investors should seek financial advice regarding the appropriateness of investing in any securities of investment strategies discussed. Not all investments are suitable for all investors.
The information herein is not legal, such as trust or estate planning, advice, or tax advice. Any such information is provided for illustrative purposes only and must not be relied upon without the benefit of the advice of your lawyer and/or tax professional. Lido specifically disclaims any liability from any reliance on such information. Lido is not a legal service provider or tax professional and does not offer legal or tax advice. Should you desire to obtain tax or legal services or advice, you must enter into your own, independent engagement agreement with a licensed attorney or tax professional.
Lido specifically disclaims any and all liability arising from the information or illustrations presented in these materials and is not responsible for the consequences of any decisions or actions taken as a result.